Lost in Translation: A Japanese Buyer's Field Guide to American Mortgage Terminology
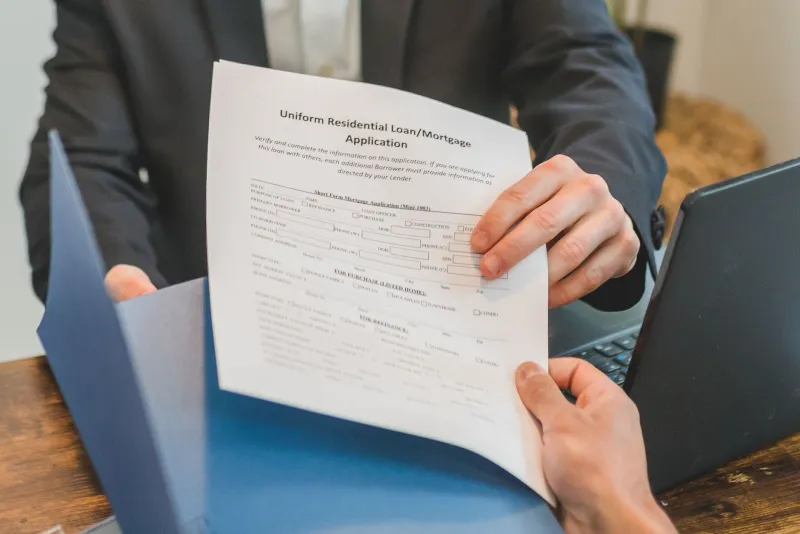
There is a particular kind of discomfort that comes from nodding along in a conversation you do not fully understand. For many Japanese buyers sitting across from an American loan officer for the first time, that discomfort is familiar. The words are English. The concepts, however, are something else entirely.
American mortgage professionals speak with practiced confidence, moving quickly through terms that carry enormous financial weight. Some of that terminology is straightforward once explained. But much of it carries layers of implication — unspoken assumptions, conditional meanings, and industry shorthand that can easily mislead a buyer who is already navigating an unfamiliar system in a second language.
This guide is designed to slow that conversation down. To name the terms that matter most, explain what they actually mean, and help you recognize the moments when you should pause, ask again, and confirm in writing.
Why Mortgage Jargon Is Especially Disorienting for Japanese Buyers
In Japan, the home lending process tends to be more standardized. Interest rates, loan structures, and documentation requirements follow relatively predictable patterns, and borrowers typically interact with a single institution through a defined process. The American system, by contrast, is decentralized and highly variable. Rates differ by lender. Loan products multiply. And loan officers — who are often commissioned salespeople as much as financial advisors — have both the incentive and the vocabulary to steer conversations in particular directions.
For Japanese buyers, the challenge is compounded by cultural communication norms. In many professional contexts in Japan, expressing confusion or asking repeated questions can feel impolite or suggest a lack of preparation. American loan officers may interpret silence as comprehension. It rarely is.
Understanding this dynamic is the first step. The second is learning the language itself.
The Terms That Carry the Most Risk
Pre-qualification vs. Pre-approval
These two phrases sound nearly identical and are often used interchangeably in casual conversation. They are not the same thing. A pre-qualification is an informal estimate based on self-reported financial information — it carries no binding weight and does not mean a lender has reviewed your actual documents. A pre-approval, by contrast, involves verified income, credit history, and asset documentation. It is the only form of lender endorsement that sellers and their agents take seriously in a competitive market.
When a loan officer says you are "pre-qualified," ask directly: "Has my documentation been reviewed and verified?" If the answer is no, you are not yet in a strong position to make an offer.
Rate Lock
Mortgage interest rates change daily. A rate lock is a lender's written commitment to hold a specific rate for a defined period — typically 30, 45, or 60 days — while your loan is processed. Without a rate lock, the rate you were quoted at the beginning of the process may bear no resemblance to the rate you receive at closing.
Loan officers sometimes describe rates in ways that imply stability without committing to it. Phrases like "rates are looking good right now" or "we expect rates to stay around this level" are not rate locks. Ask for the lock in writing, confirm the expiration date, and understand what happens — and who pays — if your closing is delayed beyond that window.
Points
In American mortgage terminology, one "point" equals one percent of the total loan amount paid upfront to the lender, typically in exchange for a reduced interest rate. This is sometimes called "buying down the rate." Points can make long-term financial sense if you plan to remain in the home for many years. They can also represent a significant upfront cost that surprises buyers who were not tracking the full picture of closing expenses.
When reviewing a Loan Estimate — the standardized document lenders are required to provide — look carefully at Section A, which lists origination charges. Any points being charged will appear here. Ask your loan officer to walk through this line item explicitly.
DTI — Debt-to-Income Ratio
This ratio compares your monthly debt obligations to your gross monthly income. Lenders use it to assess your capacity to repay a mortgage. A DTI of 43 percent or below is generally the threshold for conventional loans, though some programs allow higher ratios under certain conditions.
Loan officers may tell you that your DTI "looks fine" without specifying the actual number or how close it sits to program limits. If your DTI is near the boundary, small changes — a new car payment, a change in employment — can affect your eligibility. Ask for the specific figure and understand what is included in the calculation.
Escrow
The word "escrow" is used in two distinct contexts in American real estate, and confusion between them is common. During the transaction process, escrow refers to a neutral third-party account that holds the buyer's deposit until closing. After closing, escrow refers to a separate account managed by the lender that collects monthly contributions for property taxes and homeowners insurance, then pays those bills on your behalf.
When a loan officer mentions your "escrow payment," they are almost certainly referring to the second meaning — the ongoing monthly contribution built into your mortgage payment. This is not optional for most conventional loans with less than 20 percent down. Understanding what is included in your total monthly payment, often described by the acronym PITI (Principal, Interest, Taxes, and Insurance), is essential before you assess affordability.
The Phrases That Deserve a Follow-Up Question
Beyond specific terminology, there are conversational patterns that Japanese buyers should learn to recognize as signals for deeper inquiry.
- "That shouldn't be a problem." This phrase is not a commitment. Ask: "Can you confirm that in writing, and what would cause it to become a problem?"
- "We can probably get you approved." Probability is not certainty. Ask: "What conditions remain outstanding before approval is confirmed?"
- "Your closing costs will be around X." Estimates shift. Ask for a full Loan Estimate document, which lenders are legally required to provide within three business days of receiving your application.
- "This is a standard loan." Standards vary by program, lender, and borrower profile. Ask which specific loan product is being discussed and request a written summary of its terms.
Building a Documentation Habit
One of the most protective practices any buyer can adopt — and one that aligns naturally with the thoroughness valued in Japanese professional culture — is requesting written confirmation of every significant statement made during the lending process. This includes rate quotes, fee disclosures, approval conditions, and timeline commitments.
American loan officers communicate frequently by email, and most are accustomed to buyers who follow up in writing. There is nothing unusual or impolite about sending a message that says: "To confirm our conversation today, I understand that my rate lock expires on [date] and that my estimated closing costs are [amount]. Please let me know if I have misunderstood anything."
This habit protects you. It also creates a record that becomes invaluable if disputes arise before or after closing.
A Final Word on Advocacy
Navigating the American mortgage process as a Japanese buyer does not require becoming an expert in U.S. finance. It requires knowing enough to ask the right questions, recognizing when a conversation is moving too fast, and understanding that your loan officer — however helpful — is not your advocate in the way that an independent financial advisor or housing counselor would be.
If you find the terminology genuinely overwhelming, consider working with a HUD-approved housing counselor before engaging with lenders. These professionals offer free or low-cost guidance and have no stake in which loan product you choose.
At 安心住まい, we believe that feeling at home in America begins long before you receive the keys. It begins with understanding the process well enough to move through it with confidence — and with the clarity to know exactly what you are agreeing to before you sign.