Renting by Default: How Japanese Expats Can Honestly Reassess the Case for Buying a Home in America
For many Japanese families settling in the United States, the question of whether to rent or buy rarely receives the deliberate attention it deserves. The default answer is almost always renting — not because it has been carefully evaluated, but because it feels familiar, controllable, and appropriately cautious. In a culture that prizes measured judgment and dislikes unnecessary exposure to risk, renting carries an implicit respectability. Buying, by contrast, can feel presumptuous — a commitment to permanence in a place where permanence has not yet been earned.
This instinct is not irrational. It reflects values that serve Japanese households well in many financial contexts: patience, humility, and a reluctance to overextend. But in the specific landscape of American real estate, those same instincts can quietly become a liability — one that compounds over years without ever announcing itself.
The Cultural Gravity of Renting
Japanese expats arrive in America carrying a particular relationship with housing. In Japan, the rental market is sophisticated and broadly respected. Long-term renting carries none of the stigma it sometimes holds in American culture, where homeownership is frequently treated as a marker of adult success. For a Japanese professional on a multi-year assignment, or a family uncertain about the duration of their stay, renting simply makes sense — and feels right.
There is also the matter of unfamiliarity. American mortgage structures, property tax obligations, homeowners association rules, and closing cost conventions are genuinely complex for someone encountering them for the first time. The instinct to wait — to learn more, to feel more certain — is understandable. Caution in unfamiliar territory is wisdom, not weakness.
But caution has a cost. And in American real estate, that cost tends to accumulate quietly.
What Staying in Rental Costs Over Time
The financial mechanics of renting versus buying in the United States differ meaningfully from those in Japan. In most major American metropolitan areas, monthly rent payments do not build equity. They satisfy an obligation and provide shelter, but they leave no residual claim on an asset. Meanwhile, the homeowner next door — even one making a comparable monthly payment — is gradually acquiring ownership of something that may appreciate in value over time.
This is not a universal argument for buying. There are genuine scenarios in which renting is the smarter financial position. But the critical word is scenarios — plural, specific, and worth identifying honestly rather than assuming.
Consider a Japanese family that arrived in California five years ago, renewed their lease twice, and now earns a stable income with strong credit. They have remained renters not because the numbers favor it, but because the conversation about buying never truly happened. The caution that protected them in year one has simply persisted into year five, unchallenged.
Over that same period, home values in many California markets rose substantially. The down payment they would have needed in year one now represents a smaller percentage of a larger price. The window has not closed — but it has narrowed.
When Buying Actually Makes Sense
There is no universal threshold that signals the right moment to buy. But several conditions, taken together, create a genuinely favorable environment for Japanese expats considering ownership.
Stability of stay. If you have reasonable confidence that you will remain in the same metropolitan area for at least five to seven years, the transaction costs of buying — closing costs, agent commissions, and early mortgage interest — have sufficient time to be offset by equity accumulation and potential appreciation. Shorter timelines generally favor renting.
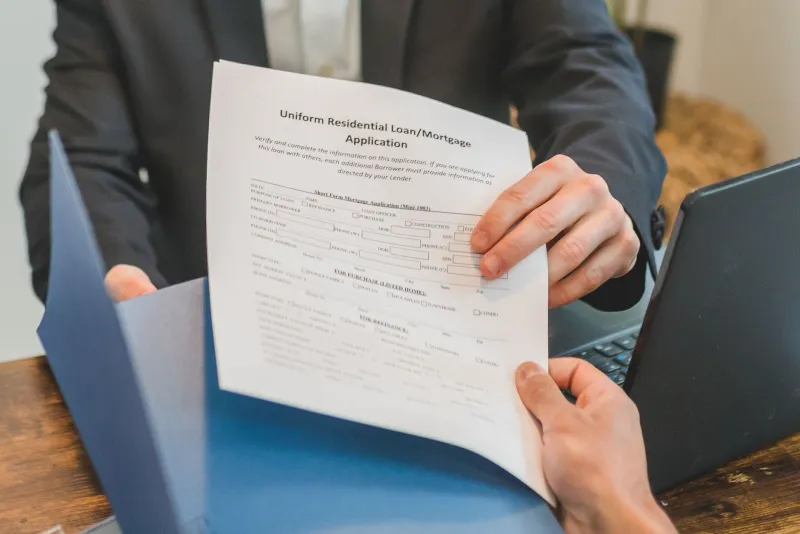
Income and credit readiness. American lenders evaluate borrowers on credit history, debt-to-income ratios, and employment consistency. Japanese expats who have been employed in the United States for two or more years and have established credit accounts are often in a stronger lending position than they realize. A preliminary conversation with a mortgage professional costs nothing and can clarify the picture significantly.
Market conditions relative to rent. In some American cities, monthly mortgage payments on a comparable property are not dramatically higher — and are sometimes lower — than prevailing rents. This is not universally true, and it shifts with interest rates, but it is worth calculating rather than assuming.
Family and life stage. For families with school-age children, the desire for neighborhood continuity, school district consistency, and the ability to personalize a home environment adds non-financial weight to the ownership side of the equation. These are legitimate considerations that a purely numerical analysis may undervalue.
Reframing Risk Without Dismissing It
The risk-averse instinct that leads many Japanese expats to default to renting is not wrong — it simply needs to be applied with more precision. The relevant question is not whether buying involves risk (it does), but whether renting is genuinely the lower-risk option for your specific situation.
Renting carries its own risks: annual rent increases, landlord decisions to sell or redevelop the property, limited ability to modify the space, and the ongoing absence of equity accumulation. These risks are real, even if they feel less dramatic than taking on a mortgage.
A more useful framework asks: What am I protecting myself from by renting, and is that risk actually present in my situation? If the answer is genuine uncertainty about your timeline or finances, renting is the appropriate choice. If the answer is simply discomfort with the unfamiliar, that is a different problem — one that more information can help address.
A Starting Point, Not a Verdict
At 安心住まい | Anshin Sumai, we recognize that the rent-versus-buy decision carries different weight for Japanese households than it might for American-born buyers. The cultural context is real, and it deserves acknowledgment rather than dismissal.
But acknowledging that context does not mean accepting it as fixed. Many Japanese expats who have gone through the process of honestly evaluating their options — with the help of a trusted real estate professional and a mortgage advisor familiar with international buyers — have discovered that ownership was more accessible, and more advantageous, than they had assumed.
The goal is not to pressure anyone into buying before they are ready. It is to ensure that the decision to rent is a decision — deliberate, informed, and revisited as circumstances change — rather than simply a habit that persists because no one has stopped to question it.
Your circumstances may genuinely favor renting. Or they may favor buying more than you realize. The only way to know is to ask the question seriously, with current numbers and honest self-assessment, rather than allowing the default answer to write itself.